

In Portugal, personal income tax rates for residents range from 12.5 to 48%, while the standard corporate income tax rate is 19%.
Portugal offers targeted tax incentives for some newcomers. Under the IFICI regime, qualifying professionals may pay a 20% rate on eligible Portuguese employment and professional income for up to 10 years.
This article explains how Portugal taxes apply to expats, investors, property owners, and businesses, as well as the main tax incentives and double taxation rules.
How taxes in Portugal work in 2026
Portugal’s tax system applies different rules depending on a person’s tax residency. For individuals, residence status determines whether Portugal taxes only domestic income or income earned worldwide[1]Source: Portal das Finanças — Tax residency rules.
Tax residency
An individual becomes a Portuguese tax resident if at least one condition applies:
- they spend more than 183 days in Portugal during a 12-month period beginning or ending in the relevant tax year;
- they maintain a home in Portugal that indicates an intention to use it as their habitual residence[1]Source: Portal das Finanças — Tax residency rules.
Portuguese tax residents pay tax on income from Portugal and abroad. Non-residents are taxed only on Portuguese-source income. The annual IRS return is filed online between April 1st and June 30th of the following year[2]Source: Portal das Finanças — Modelo 3.
Portugal tax rates at a glance
Portugal applies separate taxes to personal income, business profits, consumption, property, and employment. The applicable rates depend on the type of income or transaction, tax residency, and, in some cases, the region.
Main Portugal tax rates include:
- Personal income tax: 12.5 to 48% under the progressive IRS scale for tax residents[3]Source: Portal das Finanças — CIRS, Article 68: General IRS rates.
- Corporate income tax: 19% standard rate in mainland Portugal for tax periods beginning in 2026[4]Source: Portal das Finanças — CIRC, Article 87: Corporate income tax rates.
- VAT: 6%, 13%, or 23% in mainland Portugal, depending on the goods or services[5]Source: Portal das Finanças — CIVA, Article 18: VAT rates.
- Municipal property tax: 0.3 to 0.45% for urban property and 0.8% for rural property[6]Source: Portal das Finanças — CIMI, Article 112: Municipal property tax rates.
- Social security: employees contribute 11% of their remuneration, while employers contribute 23.75%[7]Source: Gov.pt — Social Security contributions for employees.
How to benefit from Portugal’s tax system?
Preferential tax regimes are available only to foreigners who establish Portuguese tax residency. One of the main criteria is spending more than 183 days in the country during the relevant period, which becomes possible with a Portugal residence permit.
One way for non-EU nationals to obtain Portuguese residence is through the Portugal Golden Visa. The programme grants residence by investment, issued for 2 years, subject to further 2-year renewals[8]Source: Portugal Golden Visa — AIMA official page.
Investment options include:
- €250,000+ for eligible arts and cultural heritage projects;
- €500,000+ for scientific research or non-real-estate investment funds;
- investment in a Portuguese company subject to job requirements;
- creation of at least 10 jobs.
Golden Visa holders who relocate to Portugal and become tax residents may also assess their eligibility for IFICI. Qualifying professionals benefit from a 20% tax rate on eligible Portuguese employment and professional income for up to 10 years.
Trusted by 10,000+ investors
Check your eligibility for the Portugal Golden Visa
Portugal tax rates for expats and foreign residents
Portugal tax rates for foreigners depend on two main factors:
- Whether they are Portuguese tax residents.
- Whether their income comes from Portugal or abroad.
The same personal income tax rules apply to foreign and Portuguese tax residents. Residents pay tax on worldwide income, while non-residents pay tax only on Portuguese-source income[1]Source: Portal das Finanças — Tax residency rules.
Income subject to personal income tax
Personal income tax in Portugal is known as the IRS. It covers several categories of income:
- employment income;
- business and self-employment income;
- investment income;
- rental income;
- capital gains;
- pensions[9]Source: Portal das Finanças — CIRS, Article 1: Tax base.
Portugal personal income tax rates in 2026
Tax residents pay IRS at progressive rates. Rates range from 12.5% to 48% and apply to taxable income in separate brackets:
- up to €8,342 — 12.5%;
- €8,342 to 12,587 — 15.7%;
- €12,587 to 17,838 — 21.2%;
- €17,838 to 23,089 — 24.1%;
- €23,089 to 29,397 — 31.1%;
- €29,397 to 43,090 — 34.9%;
- €43,090 to 46,566 — 43.1%;
- €46,566 to 86,634 — 44.6%;
- over €86,634 — 48%.
The rates are progressive, so moving into a higher bracket does not make all taxable income subject to the higher rate.
Non-residents pay a 25% final withholding rate on Portuguese-source employment, business and professional income. Separate rules and rates apply to other types of income[10]Source: Portal das Finanças — CIRS, Article 71: Withholding tax rates.
Portugal taxes for residents and non-residents

Tax benefits and special regimes for expats
Portugal offers targeted tax incentives to some new and returning tax residents. Eligibility depends on previous tax residence, professional activity, and the conditions of each regime.
IFICI tax regime
Portugal introduced the IFICI tax regime in 2024 to attract highly qualified professionals and support scientific research and innovation. Eligible Portuguese employment and professional income is taxed at a special 20% rate for up to 10 consecutive years. [11]Source: Portal das Finanças — IFICI tax regime.
Most foreign-source income is exempt under IFICI. Pension income and income connected with jurisdictions on Portugal’s list of preferential tax regimes follow separate rules.
Key eligibility conditions include:
- no Portuguese tax residency during the previous 5 years;
- Portuguese tax residency after relocating;
- qualifying professional activity;
- no previous use of IFICI or the former NHR regime.
Zlata Erlach,
Head of the Austrian office
IFICI is a targeted regime rather than a general tax benefit for all expats. It may apply to professionals in scientific research, higher education, information and communication technologies, healthcare, manufacturing and extractive industries, as well as certain export-oriented businesses and certified startups. Eligibility still depends on the applicant’s role, qualifications, and the type of organisation they work for.
Former Non-habitual Resident regime
Before IFICI, Portugal offered the Non-habitual Resident, NHR, regime, which gave new tax residents preferential treatment, including a 20% rate on Portuguese employment and professional income and exemptions for some foreign-source income.
The regime was closed to new applicants in 2024, although existing beneficiaries and taxpayers continue using NHR benefits for the remainder of their original 10-year period[12]Source: Portal das Finanças — Register as a Non-habitual Resident.
Returner regime for former Portuguese tax residents
Former Portuguese tax residents who return and become tax residents again by the end of 2026 may qualify for the returner regime. It excludes 50% of employment and business or professional income from taxation, up to €250,000 per year, for 5 years.
Applicants must also meet conditions on previous residence and have their Portuguese tax affairs in order[13]Source: Portal das Finanças — CIRS, Article 12-A: Tax regime for former residents.
Other taxes for individuals in Portugal
Personal income tax is only part of an individual’s tax burden in Portugal. Depending on income and employment status, residents and expats may also pay a solidarity surcharge, tax on investment income, and social security contributions.
Solidarity surcharge for high earners
Tax residents with taxable income above €80,000 pay an additional solidarity surcharge. The rates are:
- 2.5% on taxable income between €80,000 and 250,000;
- 5% on the portion exceeding €250,000[14]Source: Portal das Finanças — CIRS, Article 68-A: Additional solidarity rate.
Tax on dividends and investment income
Portuguese-source capital income, including dividends, is subject to a 28% final withholding rate. The treatment may differ depending on the taxpayer’s circumstances and applicable international tax rules[15]Source: Portal das Finanças — CIRS, Article 71: Final withholding rates.
Social security contributions
Employees contribute 11% of their remuneration to Portuguese Social Security. Employers deduct the employee’s share and transfer it together with their own contribution[16]Source: Gov.pt — Social Security contributions for employees.
Self-employed workers pay 21.4% on their applicable contribution base. Individual entrepreneurs are subject to a 25.2% rate[17]Source: Segurança Social — Contributions for self-employed workers.
Property taxes in Portugal
Property taxes in Portugal arise when real estate is purchased and while it is owned. The main taxes are property transfer tax, stamp duty, annual municipal property tax, and an additional tax on higher-value real estate.
Taxes when buying property
Property transfer tax, IMT, depends on the property type, value, and intended use. For a primary and permanent home in mainland Portugal, the 2026 scale starts at 0% for values up to €106,346 and reaches a marginal rate of 8%. Properties above €660,982 are subject to a 6% flat rate, rising to 7.5% above €1,150,853[18]Source: Portal das Finanças — CIMT, Article 17: IMT rates.
Buyers also pay stamp duty of 0.8% on a property acquisition. First-time buyers aged 35 or under may qualify for an IMT exemption on a primary home worth up to €330,539 in mainland Portugal, subject to eligibility requirements[19]Source: Portal das Finanças — Buying a home: IMT and stamp duty.
Annual municipal property tax
Property owners pay municipal property tax, IMI, based on the taxable value of their real estate.
Municipalities set the rate for urban property within the statutory range:
- 0.3 to 0.45% for urban property;
- 0.8% for rural property[20]Source: Portal das Finanças — CIMI, Article 112: IMI rates.
Additional property tax
The additional municipal property tax, AIMI, applies to residential urban property and land for construction. Individuals receive a €600,000 deduction from the total taxable property value, or €1.2 million for couples who choose joint taxation.
For individuals, AIMI rates are:
- 0.7% on the taxable amount after the deduction;
- 1% on the portion above €1 million and up to €2 million;
- 1.5% on the portion above €2 million.
The €1 million and €2 million thresholds are doubled for couples who opt for joint AIMI taxation[21]Source: Portal das Finanças — CIMI, Article 135-F: AIMI rates.
Capital gains, investment income and crypto taxes in Portugal
Portugal taxes gains from assets such as real estate, shares, securities, and crypto assets. The calculation depends on the asset type, holding period, and taxpayer’s circumstances[22]Source: Portal das Finanças — CIRS, Article 10: Capital gains.
Capital gains on property
For property sales, 50% of the net capital gain is included in taxable income. The taxable amount is subject to progressive personal income tax rates.
Since 2023, this approach also applies to non-residents who sell Portuguese property. Their worldwide income is considered when determining the applicable progressive rate[23]Source: Portal das Finanças — Taxation of property capital gains for non-residents.
Capital gains on shares and securities
Crypto asset sales are subject to capital gains tax in Portugal. Capital gains from shares and other securities are taxed at 28%. Listed securities and units in open-ended investment funds held for more than 2 years may benefit from partial exclusions from taxation.
The excluded share of the gain is:
- 10% for assets held for more than 2 but less than 5 years;
- 20% for assets held for at least 5 but less than 8 years;
- 30% for assets held for at least 8 years[24]Source: Portal das Finanças — CIRS, Article 72: Special tax rates.
Crypto tax in Portugal
Capital gains from crypto assets held for less than 365 days are taxed at 28%. Gains from crypto assets held for at least 365 days are excluded from taxation[25]Source: Portal das Finanças — CIRS, Article 10: Crypto asset capital gains.
A crypto-to-crypto exchange does not trigger immediate taxation. A crypto asset’s acquisition value transfers to the crypto asset received in exchange.
Inheritance and gift taxes in Portugal
Portugal does not impose a separate inheritance tax. Instead, inherited assets may be subject to Stamp Duty. Close family members are exempt from the 10% tax on inherited assets.
The exemption applies to:
- spouses and partners in a de facto union;
- children and grandchildren;
- parents and grandparents[26]Source: Gov.pt — Tax obligations on the transfer of assets after death.
Other beneficiaries, such as siblings, nephews, nieces, and unrelated persons, pay Stamp Duty at 10% on taxable inherited assets.
Gifts are subject to Stamp Duty. Spouses, partners in a de facto union, descendants, and ascendants are exempt from the 10% tax, although a gift of real estate remains subject to a 0.8% Stamp Duty charge.
Other beneficiaries pay 10% on taxable gifts. If the gift involves real estate, an additional 0.8% applies to the transfer[27]Source: Portal das Finanças — Donations and Stamp Duty.
Portugal taxes for businesses and companies
Companies operating in Portugal may pay corporate income tax, VAT, social security contributions, and additional surtaxes. The final tax burden depends on taxable profit, company size, location, and eligibility for tax incentives.
Corporate income tax in Portugal
Corporate income tax rates vary by region and company size. The main rates are:
- Mainland Portugal — 19% standard corporate income tax rate;
- Azores — 13.3% standard regional rate;
- Madeira — 13.3% standard regional rate;
- SMEs and Small Mid-Cap companies — 15% on the first €50,000 of taxable profit in mainland Portugal and 10.5% in Madeira and the Azores.
The standard regional rate applies to taxable profit above the preferential SME threshold where the reduced rate is available[28]Source: Portal das Finanças — CIRC, Article 87: Corporate income tax rates.
Companies with taxable profits above €1.5 million also pay a state surtax. The applicable rate depends on taxable profit and company location. Madeira and the Azores apply reduced regional surtax rates compared with mainland Portugal[29]Source: Portal das Finanças — CIRC, Article 87-A: State surtax.
Corporate surtax rates by region
VAT rates
Businesses subject to VAT charge different rates depending on the goods or services supplied. In mainland Portugal, the main VAT rates are:
- 6% reduced rate for goods and services, including basic food products, books and newspapers, medicines, and passenger transport;
- 13% intermediate rate for goods and services listed in List II annexed to the Portuguese VAT Code, such as ready-to-eat takeaway and home-delivery meals, mineral and table water, and common wines;
- 23% standard rate for other taxable goods and services[30]Source: Portal das Finanças — CIVA, Article 18: VAT rates.
Employer social security contributions
For most employees of commercial companies, employers contribute 23.75% of gross remuneration to Social Security. Employees contribute another 11%, which the employer withholds and transfers to Social Security[16]Source: Gov.pt — Social Security contributions for employees.
Madeira Free Trade Zone tax incentive
Companies licensed in the Madeira Free Trade Zone by December 31st, 2026 may benefit from a 5% corporate income tax rate on eligible income until December 31st, 2033.
To access the regime, a company must:
- Start operations within 6 months.
- Create 1—5 jobs during that period.
- Invest at least €75,000 in fixed tangible or intangible assets within the first 2 years, or create at least 6 jobs within the first 6 months.
The reduced rate applies only to eligible activities and is subject to annual taxable income limits linked to the number of jobs maintained[31]Source: Portal das Finanças — Tax Benefits Statute, Article 36-A: Madeira Free Trade Zone.
Companies licensed in the Madeira Free Trade Zone by December 31st, 2026 may apply a 5% corporate income tax rate to qualifying income until December 31st, 2033.
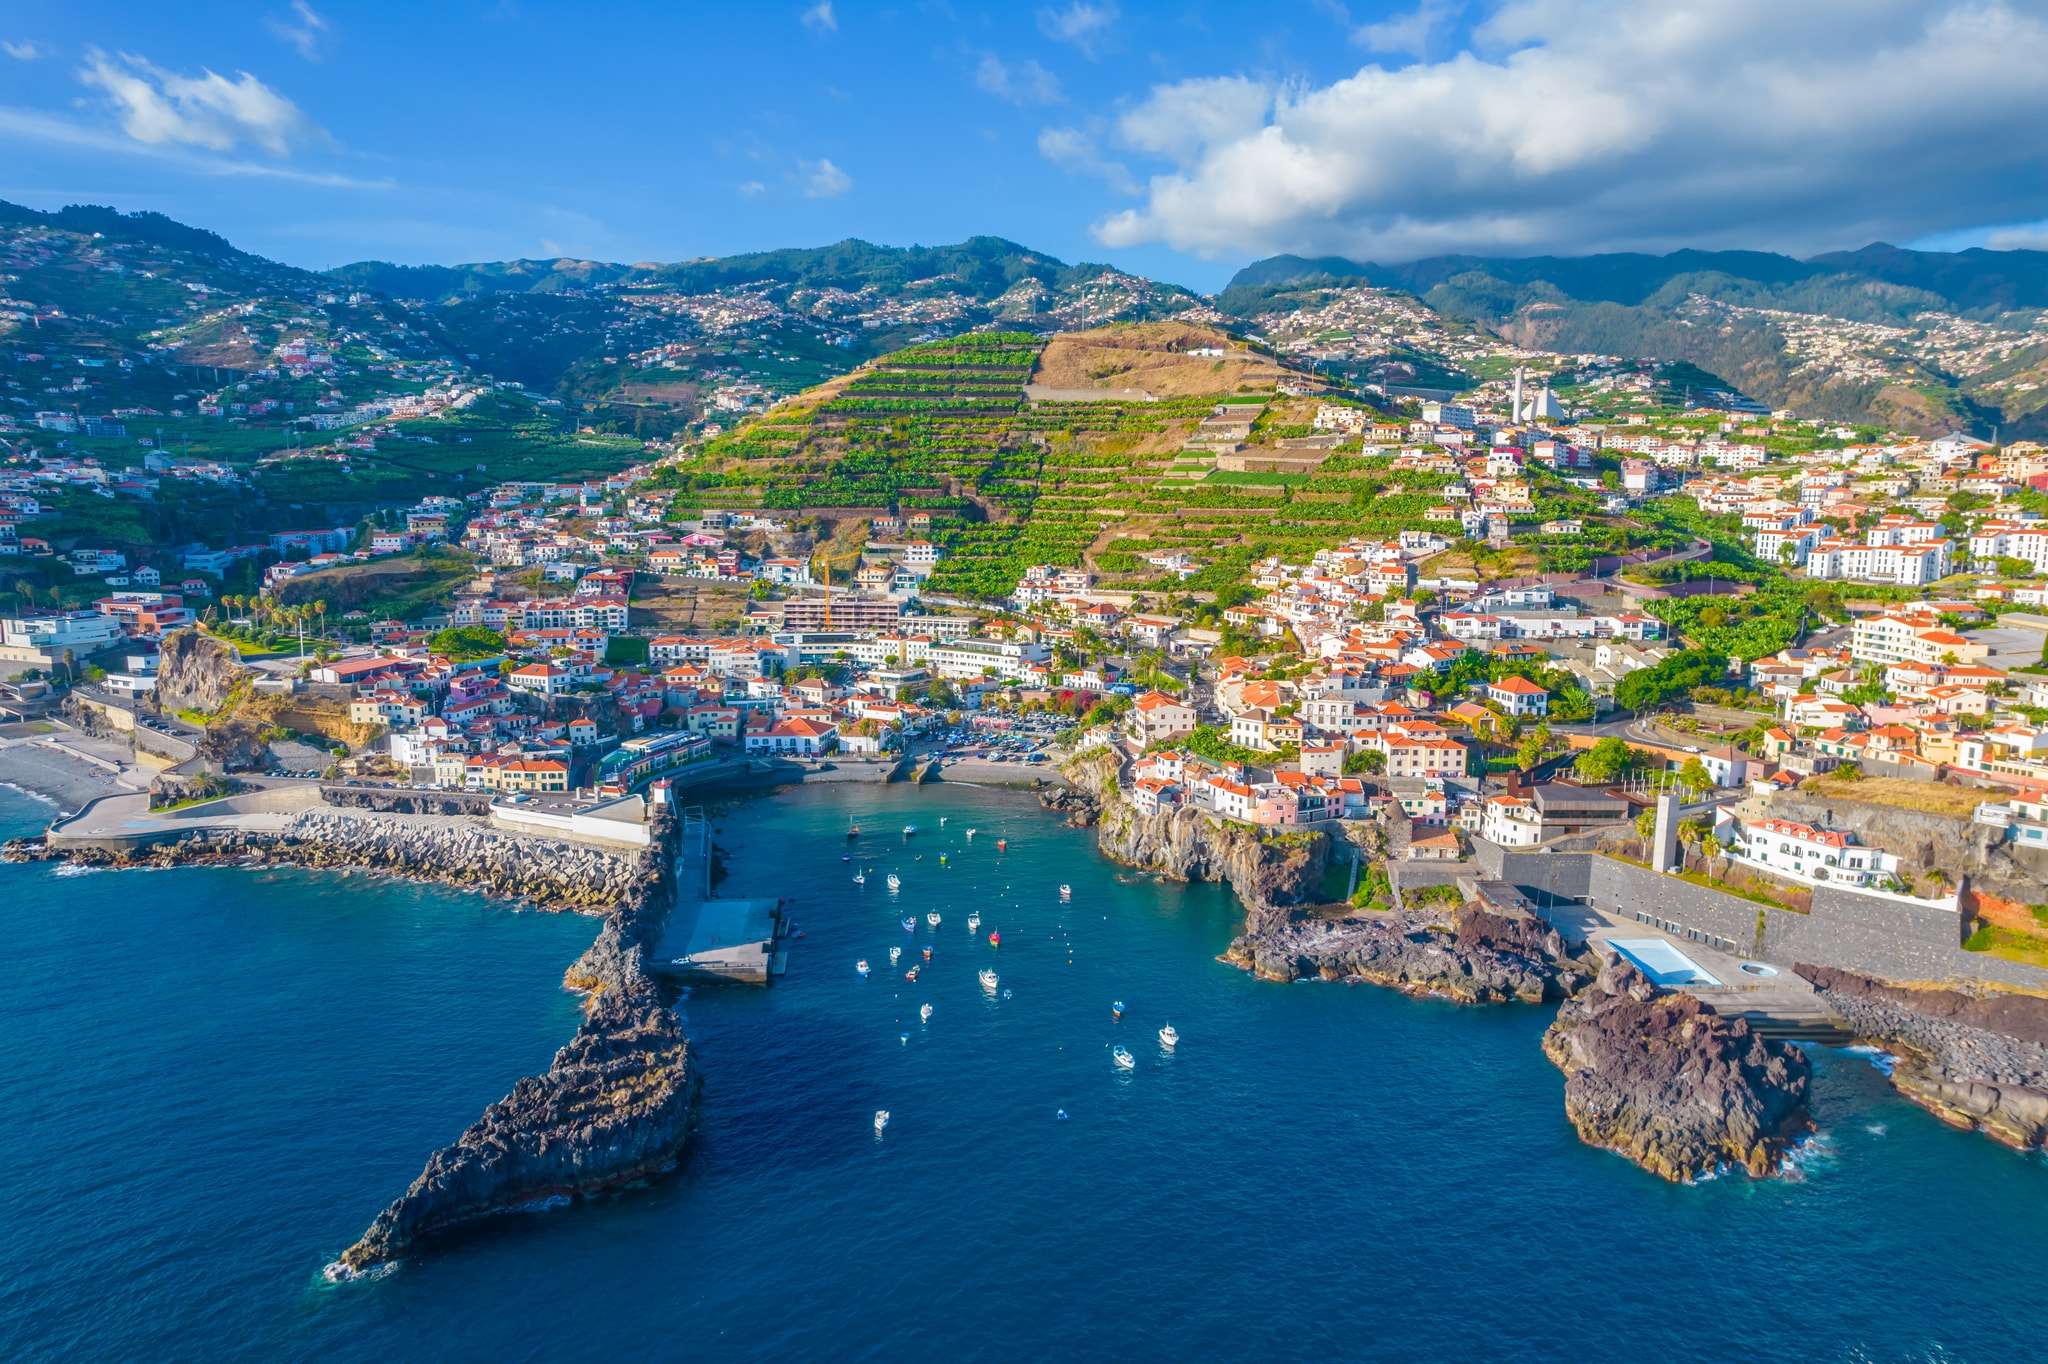
Madeira is an autonomous region of Portugal in the Atlantic Ocean. The archipelago lies around 1,000 km southwest of mainland Europe, and a flight from Lisbon takes 90 minutes
How Portugal avoids double taxation
Portugal uses double taxation treaties and foreign tax credits to reduce cases where the same income is taxed in Portugal and another country. Portuguese tax residents may credit foreign tax paid against Portuguese tax[32]Source: Portal das Finanças — IRS international relations FAQs.
Double taxation treaties
Portugal has signed 79 double taxation conventions, 78 of which are currently in force. The network includes agreements with major jurisdictions such as the US, the UK, Canada, China, India, Japan, and the UAE, as well as many EU countries.
Depending on the treaty, the rules determine:
- tax residence when both countries consider a person resident;
- taxation of employment and business income;
- treatment of dividends, interest, and royalties;
- taxation of pensions, property income, and capital gains[33]Source: Portal das Finanças — Double taxation conventions.
US—Portugal tax treaty
Portugal and the US have an income tax treaty that allocates taxing rights between the two countries and helps prevent the same income from being taxed twice. In some cases, income may still be taxable in both countries, but tax paid in one country may be credited against tax due in the other.
Taxpayers may still need to file returns in both jurisdictions and claim or report the relevant foreign tax credit[34]Source: Portal das Finanças — CIRS, Article 81: Elimination of international double.
Portugal and the US also have a Social Security Totalisation Agreement. It coordinates social security coverage, helps prevent dual contributions, and allows qualifying periods of coverage in both countries to count towards certain benefits[35]Source: US Social Security Administration — Totalization Agreement with Portugal.
How to become a tax resident in Portugal
Becoming a Portuguese tax resident depends on meeting the statutory residence criteria and updating the taxpayer’s status with the Portuguese Tax and Customs Authority.
For foreigners planning to live in Portugal long term, tax residency determines the scope of income subject to Portuguese taxation. Residents pay tax on worldwide income, while non-residents are taxed only on Portuguese-source income.
4—12 months
Obtain the right to reside in Portugal
Foreigners planning to spend more than 183 days in Portugal need a legal basis for long-term residence, such as a residence visa or residence permit.
Portugal offers several routes to get a residence permit, including the Golden Visa, D7 Visa, Digital Nomad Visa, and Global Talent Visa for highly qualified professionals.
183+ days a year
Meet a tax residency criterion
An individual becomes a tax resident after spending more than 183 days in Portugal during a relevant 12-month period. Having a home intended as a habitual residence may also establish tax residency.
An individual becomes a tax resident after spending more than 183 days in Portugal during a relevant 12-month period. Having a home intended as a habitual residence may also establish tax residency.
1 day
Obtain a NIF
The Portuguese tax identification number consists of 9 digits and is required to interact with the Tax and Customs Authority. Foreigners may request it in person or through an authorised representative online.
The Portuguese tax identification number consists of 9 digits and is required to interact with the Tax and Customs Authority. Foreigners may request it in person or through an authorised representative online.
1 day
Update tax residency status
Once a person meets the residence criteria, they change their tax address from a foreign address to a Portuguese one. The change must be reported to the Tax and Customs Authority within 60 days.
The NIF remains the same when a taxpayer changes from non-resident to resident status. Tax residency affects the scope of income subject to Portuguese taxation and the individual’s subsequent reporting obligations.
Residence options that may lead to Portuguese tax residency
Portugal offers several residence routes for investors, financially independent persons, remote workers, and highly qualified professionals. A residence visa or permit does not automatically establish Portuguese tax residency.
Tax residency generally arises when a person spends more than 183 days in Portugal during the relevant period or maintains a home intended as their habitual residence.
Portugal Golden Visa for investors
Portugal Golden Visa grants a residence permit to third-country nationals who make a qualifying investment. Holders receive the right to reside and work in Portugal, travel within the Schengen Area, and apply for family reunification.
Current investment options include:
- €250,000+ for eligible arts or cultural heritage projects;
- €500,000+ for scientific research;
- €500,000+ in non-real-estate investment funds;
- €500,000+ for establishing or capitalising a Portuguese company and creating 5 jobs;
- creation of at least 10 jobs, with no financial threshold.
Golden Visa holders must spend at least 7 days in Portugal during the first year and 14 days during each subsequent two-year period.
Portugal D7 Visa for financially independent persons
Portugal D7 Visa is intended for retirees and other foreigners who live on their own regular income. Applicants provide evidence of income, accommodation, and sufficient means to support themselves while residing in Portugal.
The applicant must prove a passive income of at least €920 per month. An additional rise of 50% applies to a spouse and of 30% to a child.
D7 holders are expected to make Portugal their main place of residence. A temporary residence permit may be cancelled if the holder is absent from Portugal for more than 6 consecutive months or 8 non-consecutive months during its 2-year validity.
This requirement results in meeting the 183-day tax residency criterion and becoming a Portuguese tax resident.
Portugal Global Talent Visa for highly qualified professionals
Portugal Global Talent Visa route is based on the residence framework for research and highly qualified activities. It covers eligible doctoral students, researchers, university teaching staff, and professionals carrying out highly qualified work in Portugal.
Applicants provide documents confirming their activity. Depending on the applicant’s profile, these include an employment contract, promise of employment, service agreement, research grant, or evidence of the professional qualifications required for the position.
Professionals who relocate and meet the Portuguese tax residency criteria become taxable in Portugal on worldwide income. Some specialists also qualify for the IFICI tax regime if they meet its separate residence and professional requirements.
How Immigrant Invest can help with Portugal residence and tax planning
Immigrant Invest assists foreigners who plan to obtain residence in Portugal and assess the tax implications of relocation. The process starts with reviewing the applicant’s goals, circumstances, and suitable residence route.
Immigrant Invest supports applicants for Portugal residence permits throughout the process:
- Preliminary Due Diligence. The Compliance Department reviews the applicant’s background and identifies potential risks before the application process begins.
- Residence route selection. Experts compare available options, such as the Portugal Golden Visa, D7 Visa, Digital Nomad Visa, and Global Talent Visa.
- Document preparation. The team prepares a personalised document checklist and coordinates translations, legalisation, and submission.
- Relocation support. Assistance may include obtaining an NIF, opening a bank account, arranging accommodation, and coordinating residence appointments.
Immigrant Invest does not provide tax advice. When tax planning is required, the company can introduce clients to licensed Portuguese tax advisers who assess tax residency, income sources, available incentives, and cross-border tax obligations.
Key points about Portugal taxes in 2026
- Portuguese tax residents pay tax on worldwide income, while non-residents are taxed mainly on Portuguese-source income.
- Portugal tax rates for residents range from 12.5 to 48%, with higher rates applying to higher portions of taxable income.
- Businesses pay corporate income tax and other levies. The standard corporate income tax rate in mainland Portugal is 19%, while VAT reaches 23% under the standard mainland rate.
- Property owners face taxes at purchase and during ownership. These include IMT, Stamp Duty, annual IMI, and AIMI for qualifying higher-value property.
- Portugal offers targeted tax incentives. Qualifying professionals may benefit from the IFICI regime of 20% income tax for up to 10 years.
- Portugal has signed 79 double taxation agreements, including with the US, the UK, Canada, China, India, Japan, and the UAE. These agreements help residents avoid paying tax twice on the same income.
- To become a tax resident in Portugal, foreigners must first obtain a residence permit, for example through the Portugal Golden Visa.
Immigrant Invest is a licensed agent for citizenship and residence by investment programs in the EU, the Caribbean, Asia, and the Middle East. Take advantage of our global 15-year expertise — schedule a meeting with our investment programs experts.
 Trusted by 10,000+ investors